
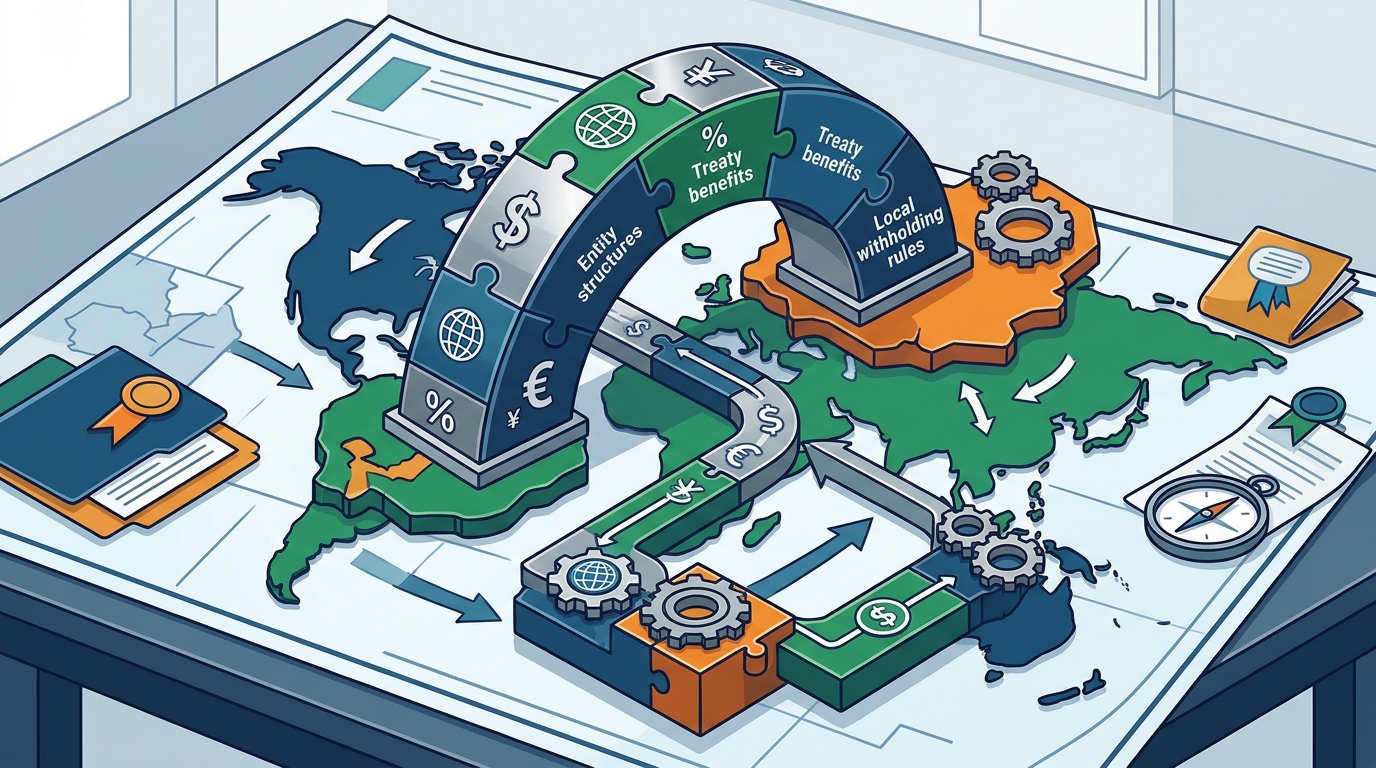
International M&A tax strategy is the process of structuring a cross-border deal to minimize tax liabilities while ensuring compliance in all relevant jurisdictions. Before closing, buyers must evaluate entity structures, treaty benefits, and local withholding rules. Firms like BridgehouseLaw help clients navigate these complexities to protect deal value and ensure smooth post-closing integration. For additional details, review the Contact Bridgehouse Law.
Entity Structure and Holding Companies
The choice of acquisition vehicle is the most critical tax decision in international M&A. Tax-efficient structuring often requires setting up holding companies in favorable jurisdictions to coordinate intercompany financing and leverage available treaty benefits. This approach allows buyers to manage cash flows and repatriate profits with reduced friction. For example, a U.S. buyer acquiring a European target might use a holding company in a treaty-friendly jurisdiction to optimize dividend flows. The implication is that the initial structure dictates the long-term tax posture of the combined entity. For additional details, review the BridgehouseLaw Business Legal Solutions.
Utilizing Tax Treaties and Withholding Rules
Double taxation treaties are agreements between two countries that allocate taxing rights and reduce withholding taxes on cross-border payments. Understanding these treaties is essential for managing the tax cost of dividends, interest, and royalties paid between the buyer and the target. For instance, a specific treaty might reduce the withholding tax on dividends from 30% to 5%. Buyers must verify that the structure qualifies for treaty benefits, as some jurisdictions have anti-abuse rules. This ensures that the expected tax savings are actually realized and not clawed back by tax authorities. For additional details, review the .
Asset vs. Stock Purchase Considerations
The distinction between an asset purchase and a stock purchase significantly impacts the tax basis and future depreciation benefits. An asset purchase allows the buyer to step up the tax basis of the acquired assets, leading to higher depreciation deductions and lower taxable income in future years. In contrast, a stock purchase generally does not provide a basis step-up, which can result in higher ongoing tax liabilities. For example, acquiring a manufacturing plant as an asset purchase can provide substantial tax shields through accelerated depreciation. The choice depends on the target's asset composition and the buyer's long-term tax planning goals.
Post-Closing Integration and Compliance
Tax planning does not end at closing; post-closing integration requires ongoing compliance with multi-jurisdictional tax laws. Companies must align their transfer pricing policies, manage intercompany loans, and ensure that their operations comply with local tax regulations. For example, a company with operations in the U.S. and Germany must ensure that its intercompany pricing reflects arm's length standards to avoid transfer pricing adjustments. This continuous compliance is vital to avoid penalties and maintain the integrity of the initial tax structure. Firms with global offices, such as BridgehouseLaw, provide the local expertise needed to manage these ongoing obligations.
Key Takeaways
- Entity structure is the foundation of international M&A tax planning.
- Tax treaties can significantly reduce withholding taxes on cross-border payments.
- Post-closing compliance is essential to maintain the benefits of the initial structure.
- Local expertise is critical for navigating multi-jurisdictional tax laws.
Frequently Asked Questions
What is the main benefit of using a holding company in M&A?
A holding company can optimize dividend flows and leverage tax treaties to reduce withholding taxes.
How do tax treaties affect M&A deals?
Tax treaties reduce withholding taxes on cross-border payments like dividends, interest, and royalties.
What is the difference between an asset and stock purchase in terms of tax?
An asset purchase allows for a basis step-up, while a stock purchase generally does not.
Why is post-closing tax compliance important?
Post-closing compliance ensures that the initial tax structure remains valid and avoids penalties.
How can a law firm help with international M&A tax planning?
A law firm provides local expertise and strategic guidance to navigate multi-jurisdictional tax laws.